A good deal at closing isn’t enough for investors to make a profit. They generate returns through smart renovations, timing, and resale strategy. After-repair value, or ARV, is the estimated price a property could sell for once renovations are complete. This number influences financing, renovation plans, and resale pricing. Residential investment loans can maximize ARV by providing renovation capital that supports the specific upgrades buyers pay for in that neighborhood.
Calculating ARV
After-repair value is the projected market value of a property after renovations are complete. Appraisers and lenders analyze comparable sales, neighborhood trends, and property condition to support that number. Investors use ARV to calculate potential profit and determine renovation budgets. Consequently, inflated projections distort the entire investment plan.
Comparable Sales
Comparable sales are used to support the ARV when they match your property’s key features, such as location, size, number of bedrooms and bathrooms, and general style. Appraisers look for recent sales, then adjust for meaningful differences, such as an extra bath, a garage, or a larger living area.
Neighborhood Trends
Neighborhood trends show whether buyers move up in price, stay flat, or pull back, and that movement changes how aggressive your ARV should be. Appraisers and lenders may review sale-to-list ratios, days on market, and how quickly updated homes go under contract compared to dated ones.
Property Condition Review
Condition impacts ARV because buyers pay for “move-in ready,” and they discount uncertainty. Lenders and appraisers pay close attention to big-ticket items like roof life, HVAC age, plumbing, electrical, and signs of water intrusion. While cosmetic finishes matter, structural and mechanical issues tend to drag value down faster.
Budget With Purpose
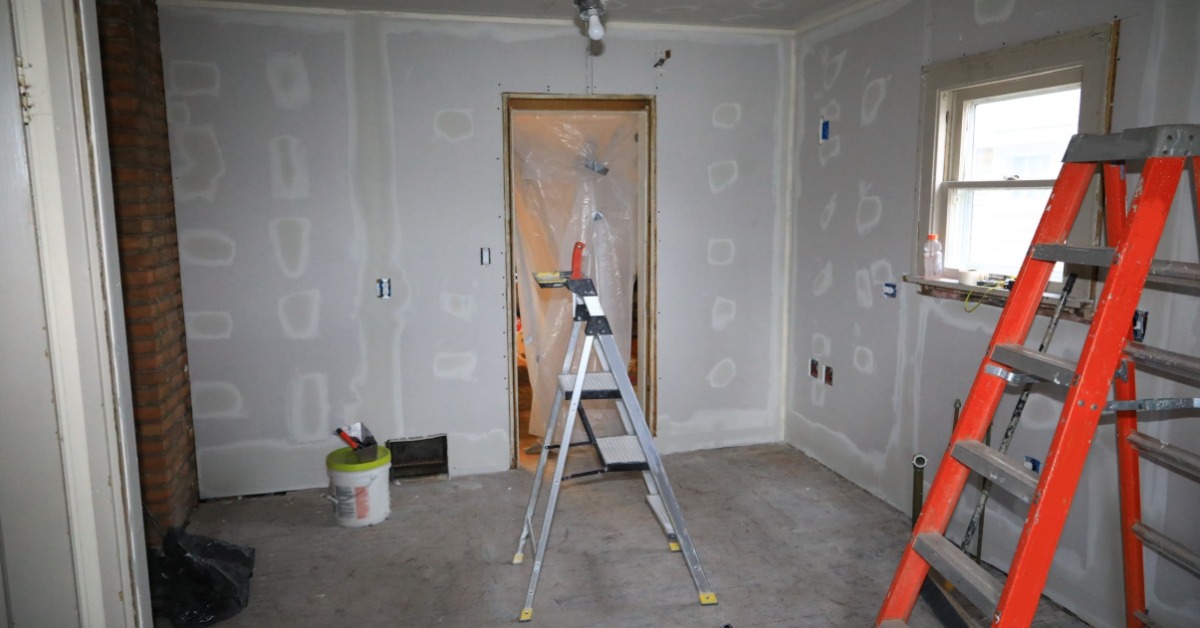
A rehab budget shouldn’t feel like a wish list, and it shouldn’t feel like a guess either. Start by outlining the upgrades the home needs to compete with other renovated listings in the same micro-market. Then set aside contingency money, since older houses often reveal new issues when you open up walls.
The smartest budgets separate value drivers from nice extras. A kitchen refresh might anchor the value, while a fancy built-in bar might just eat margin. Itemized budgets help you communicate clearly with your lender and your contractor, which keeps the project moving.
Choose High-Impact Upgrades
Buyers tend to respond to upgrades they can see and feel right away, like clean kitchens, updated baths, and consistent flooring. That said, your neighborhood sets the ceiling, so you want upgrades that match what local buyers expect.
Aim for cohesive choices that photograph well, since listing photos do heavy lifting. The upgrades that usually support ARV share one trait: they align with what comparable renovated homes already offer.
Use this checklist to stay focused on improvements that buyers value in many markets:
Repair or replace worn roofing components.
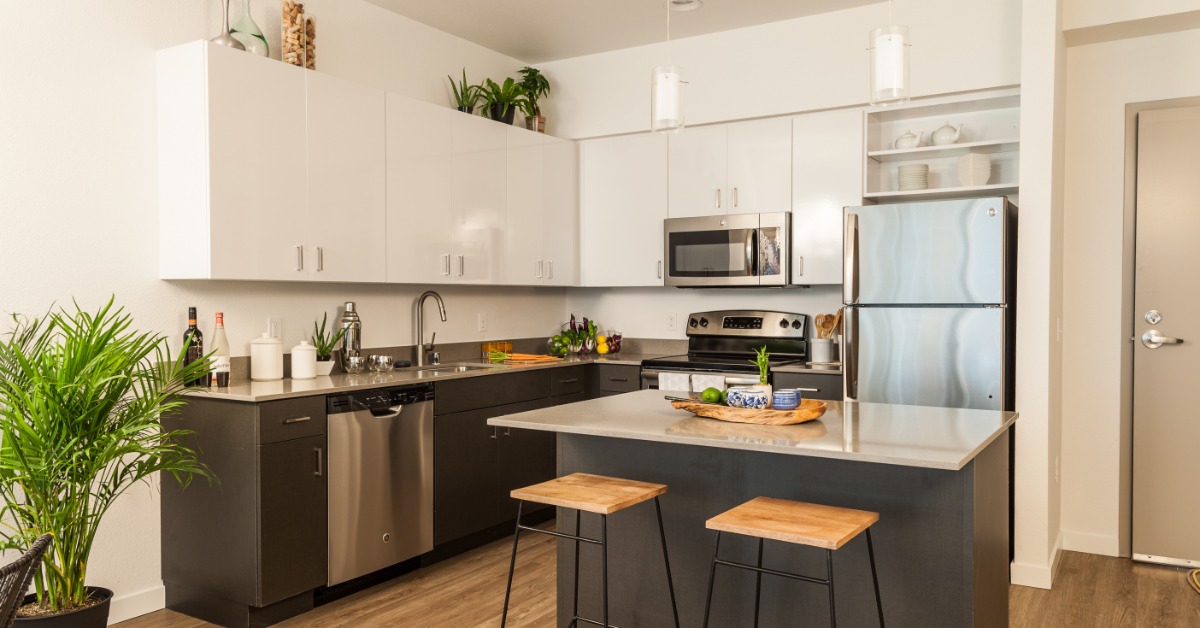
Update kitchens with durable, simple finishes.
Refresh bathrooms with modern fixtures and lighting.
Improve curb appeal with paint and landscaping.
Address safety issues such as wiring defects.
Fast Close, Steady Upgrades
Residential investment loans can maximize ARV by preventing cash flow gaps that slow renovation work. With the right structure, you can close quickly, then access rehab funds as you complete each phase. That steady funding supports higher-impact upgrades like kitchens, baths, and core repairs that buyers pay extra for.
When money arrives at the right time, contractors can more easily stay on schedule, and the project reaches a truly market-ready finish. A realistic timeline and solid documentation also make inspections and disbursements smoother, which helps keep the rehab moving.
Draws, Timing, and Cash Flow
Cash flow problems can bring your renovation projects to a complete halt. Each stage of work needs money at the right moment, from demolition to rough-in to finishes. If the draws don’t match the order of operations, contractors slow down, and the renovation timeline stretches.
A tight timeline supports ARV because buyers and appraisers lean on recent, “current” comps when they price a finished home. When a rehab drags out, the market can shift, and those comps may no longer reflect the most accurate pricing window.
At the same time, every extra week adds holding costs that eat into your margin and put more pressure on your exit price. Smooth draw timing keeps crews moving, limits holding costs, and helps you hit a market-ready finish that supports top-dollar ARV.
Managing Risk During Rehab
Risk management protects your ARV by preventing the delays and rework that buyers never pay extra for. Start with a contractor you trust, then build checkpoints into the timeline so you catch issues early. A simple weekly walkthrough can save a month of headaches later.
Review these five risk controls before the first day of demo:
Confirm permits and inspection requirements early.
Order long-lead materials before demolition begins.
Keep a contingency line item for hidden repairs.
Document work progress with dated photos.
Reconfirm scope changes in writing.
Owner-Occupied Hard Money Loans
Owner-occupied hard money loans are for buyers who want to live in the home but need financing for a property that requires repairs. These loans fund upgrades that turn the home from a fixer-upper to a finished home, which supports stronger comps and a higher post-renovation valuation. Owner-occupied hard money loans in Florida are particularly appealing when a home’s condition, the seller’s timeline, or the renovation scope makes conventional financing a poor fit.
This loan can make sense when you’re buying a dated property in a desirable area, and you want to renovate quickly instead of waiting through a long underwriting process. It also supports a focused rehab plan where you tackle value drivers first, document the work, and finish with a cohesive, appraiser-friendly result.
These are some of the common improvements borrowers fund to support ARV and livability:
Kitchen refreshes, including cabinets and counters.
Bathroom updates, including tile, vanities, and fixtures.
Flooring replacement and interior paint.
Roof, HVAC, plumbing, or electrical repairs.
Curb appeal upgrades like exterior paint, windows, and siding.
ARV grows when your plan stays realistic, your upgrades match the neighborhood, and your financing supports the timeline. Residential investment loans give you a way to fund the work that buyers reward, as long as you stay disciplined with scope and documentation. Using closely matched comparable sales, clear condition notes, and a buyer-driven budget helps you keep your ARV targets realistic.
In residential investing, timing determines who wins the deal. A strong renovation plan means little if financing slows down the closing process. Hard money helps residential flippers close quickly by matching funding speed to the pace of competitive markets.
This form of private lending provides short-term, asset-based capital secured by real estate. Instead of focusing primarily on borrower income, hard money lenders evaluate the property’s value and the project’s resale potential. This structure allows approvals and closings to move faster than many traditional mortgage options.
Certainty Wins Deals
Closing speed influences more than logistics; it shapes how sellers interpret your offer. Sellers prioritize smooth transactions without unexpected financing delays. Extended underwriting timelines create doubt and increase perceived risk.
Hard money enables flippers to make offers backed by verified capital. Additionally, shorter closing windows reduce hesitation from sellers and listing agents. In short, strong financing positions your bid more favorably in negotiations.
How Slow Funding Creates Uncertainty
Slow funding introduces multiple points of doubt into a transaction. As approval timelines stretch, sellers begin to question whether underwriting issues, appraisal gaps, or documentation problems could derail the deal. Listing agents may advise clients to consider backup offers when financing appears uncertain. That hesitation weakens negotiating power and shifts leverage away from the buyer.
Strengthening Your Negotiation Position
Residential investors compete with cash buyers, seasoned operators, and institutional groups that already have capital lined up. In that environment, financing becomes part of the offer itself. Speed, certainty, and structure all influence how sellers evaluate competing bids.
Hard money reduces dependence on extended underwriting timelines that can weaken contract terms. Shorter approval cycles allow investors to present cleaner, more decisive offers. Hard money helps residential flippers close quickly and negotiate from a position of strength.
Reducing Financing Contingencies
Financing contingencies introduce uncertainty into a contract. Long approval windows give sellers reason to question whether a deal will actually close. Hard money typically compresses those timelines, which reduces conditional language and improves perceived reliability.
Stronger offers often share several structural advantages:
Clearly defined and shorter closing windows.
Limited or simplified financing contingencies.
Proof of funds from an active lender.
A realistic renovation scope.
A defined resale or exit timeline.
Each of these elements signals preparation and confidence. Sellers gravitate toward buyers who minimize risk, and well-structured financing improves acceptance odds before renovation begins.
Proof of Funds Strategy
Proof of funds carries weight beyond a simple document. Listing agents frequently request it before advising sellers to accept an offer. Backing a bid with verified capital communicates readiness and professionalism.
Depending on the deal structure, private money lenders can provide proof of funds early in the process, sometimes before full underwriting concludes. That documentation shows sellers you have access to deployable capital. With verified funding in place, competitive leverage begins the moment your offer hits the table.
Auction and Foreclosure Scenarios
Some of the strongest margins in residential flipping come from distressed acquisitions and auction purchases. These transactions operate on compressed timelines and firm closing deadlines. Traditional lenders, including large national banks, regional banks, and conventional mortgage lenders, rely on standardized underwriting processes that typically cannot close within such compressed timeframes.
Hard money aligns with these high-speed acquisition windows. Asset-based evaluation allows lenders to focus on property value and exit strategy rather than extensive income documentation. Investors gain access to opportunities that slower funding structures would eliminate.
Advantages of In-House Lending
Not all private lenders structure their operations the same way. Some act primarily as intermediaries, connecting borrowers to external capital sources, while others handle underwriting, funding, and servicing internally. In-house lending keeps the entire process under one roof, which directly affects speed and consistency.
Faster Decision Cycles
When underwriting and funding teams work within the same organization, fewer approval layers slow the process. Questions are routed directly to decision-makers, which shortens turnaround times and supports faster closings.
Clearer Communication
Direct access to the lending team reduces miscommunication that can occur when multiple third parties are involved. Investors receive answers faster, which helps keep contracts and renovation timelines on track.
Greater Process Control
In-house lenders oversee the loan from application through payoff. That continuity improves coordination across underwriting, closing, and draw disbursements. Investors benefit from predictable execution throughout the transaction lifecycle.
Handling Appraisal and Condition Issues
Distressed properties rarely meet the strict habitability standards required by conventional lenders. Major repairs, utility interruptions, or deferred maintenance frequently stall bank approvals.
Hard money lenders focus on projected after-repair value (ARV) rather than current cosmetic condition. Asset-based evaluation allows flippers to purchase properties that require improvement. In this system, financing supports the renovation plan rather than penalizing the current state.
What Influences ARV
After-repair value depends on recent comparable sales, location, property size, and the quality of planned renovations. Investors typically analyze similar properties that have sold within the past few months to estimate a realistic resale price. Accurate renovation budgeting and market awareness help prevent overestimating ARV and protect projected profit margins.
Aligning Financing With Exit Strategy
Hard money works best when paired with a clearly defined resale or refinance timeline. Investors should confirm that the renovation scope, market demand, and pricing strategy align with the loan term. A disciplined exit plan reduces carrying costs and reinforces the advantage of fast closings.
Portfolio-Level Growth
Speed influences more than a single acquisition; it shapes how many deals an investor can complete within a year. When closings happen faster, capital turns over more efficiently, allowing investors to move from one project to the next without prolonged downtime.
That improved velocity directly affects overall return on invested funds. Hard money supports this cycle by making capital available again shortly after resale.
Instead of waiting months for traditional financing resets, investors can redeploy funds into new acquisitions more quickly. Over time, this consistency transforms growth from reactive deal-chasing into a deliberate expansion strategy.
Successful flippers understand that timing affects acquisition, renovation, and resale alike. Hard money provides the flexibility and speed required to compete confidently in compressed markets. By reducing uncertainty and improving capital turnover, this financing structure supports immediate deal performance and broader portfolio expansion. Contact BridgeWell Capital for a hard money loan that supports fast closings and disciplined execution from purchase to resale.
Damaged credit can impact your ability to take out a loan, creating a cyclical cycle that may feel impossible to overcome. To repair your credit, it is important to understand how it became damaged in the first place. There are many reasons your credit might be in rough shape but, thankfully, there are also many ways to repair your credit into something workable. Here are three ways that your credit might be damaged and how you can go about fixing it:
No Credit:
Credit – “The ability of a customer to obtain goods or services before payment, based on the trust that payment will be made in the future.” (Oxford Languages)
A lack of credit prevents you from taking out a loan along with barring you from other financial opportunities. Without a credit score, it can be difficult or even impossible to purchase a home, rent a home, finance a vehicle, or take out a loan, among other things. Think of it this way; every time you rent something, the company you’re renting from is gambling on the fact that you’ll return that entity. Credit scores tell a company if you are to be trusted. A good one shows that you have a history of borrowing money and paying it back promptly. A bad credit score shows that you have either not paid back borrowed money or taken too long to pay back borrowed money. No credit score is often just as bad. It tells companies that you don’t have a history, meaning they cannot gauge if you’re trustworthy. More often than not, they will not be willing to take this uncalculated risk.
The good news is that credit is relatively easy to build passively. If you have no credit, the first thing you should do is apply for a credit card. You’ll want to shop around for something that fits your needs to ensure you’re getting the card that will benefit you the most. Once you have a card, pick some expense that you would be paying for regardless, something small that you can put on the card and pay it off every month without issue. To achieve and maintain a good credit score, you have to make sure you’re paying off your credit card every month. Most credit card companies allow you to set up automatic payments so that no action is required on your part to ensure you don’t miss a payment.
If you’re seeking a loan and need to build your credit quickly and passively, another easy thing you can do is find a responsible family member or friend who has a good credit history. Ask them to add you to their card. They are not going to give you their card, nor will you have access to any of their finances, but by adding you to their account you can benefit from their good credit history. This will allow you to become eligible for loans while you work on building your own credit history in the background.
Utilization:
Credit Utilization Ratio– “Your credit utilization ratio is the amount of available credit you’re using… Only revolving credit accounts, such as credit cards or personal lines of credit, apply to your utilization ratio” (Discover).
Your credit limit is the amount of money you’ve been approved to put on your credit card. Your credit utilization ratio, also sometimes called credit utilization rate, is how much of that allotment you’re using. Why does this matter? Your credit utilization rate accounts for a significant portion of your credit score, typically around 30%, making it a big deal when it comes to trying to improve your score. If you’re using a larger portion of your credit limit, this could indicate that you’re overspending and may be unable to pay back what you’ve borrowed in a timely manner. On the other hand, a lower utilization rate, shows responsible borrowing habits, meaning you can be relied on to pay back what you owe.
So, how do you calculate your credit utilization rate? All you need is some basic math:
Add up your current outstanding balance on all your credit accounts. This is your total debt.
Add up your credit limits on these accounts. This is your total credit limit.
Divide your total debt amount by your total credit limit amount.
Multiply that amount by 100 to arrive at your credit utilization rate.
Generally, a rate between 1% and 10% is ideal but don’t panic if your rate is higher. There are plenty of ways to improve your credit utilization rate:
If you’re nearing your credit limit, it may be a good idea to ask your credit card company for a credit limit increase. If your credit limit goes up but the amount you owe on the card stays the same, your utilization goes down, which increases your credit score. This will only work if you maintain a proportionally low balance once your limit increases. It is important to keep in mind that if your credit isn’t the best initially, it is likely your increase request won’t be approved.
The easiest and most basic way to improve your utilization rate is to pay down your debt. Ensure you are paying off your balance on time and not spending beyond your means. To see the fastest results, you may want to be aware of the timing in which you are making payments. Lenders typically report your balance at the end of your billing cycle (usually every 30 to 45 days). Making a payment on your balance before the end of your billing cycle means the lower balance will be reported. However, if you wait until the cycle is closed, it is worth it to pay over the minimum amount required month to month to see a greater improvement in a shorter amount of time.
Bad payment history, bankruptcy, and foreclosure:
If you have a bad payment history, making sure you pay your bills on time is the best way you can improve this. If you’re able to, setting up automatic payments may be the best way to ensure this happens. Set it up so that the minimum owed gets paid every month on time and, if you’re able to, pay extra in addition. If you’re unable to set up automatic payments, using a reminders app or writing your payment date on your calendar could be your best option. The only way to solve bad payment history is to change your habits to make sure you have a good payment future.
As for bankruptcy and foreclosure, unfortunately, the only way to resolve these issues for good is time and quite a lot of it. While you may not be able to get your own credit score up in a timely enough manner, you can find a partner with good credit. Finding someone to partner with on your flips who has good credit is the only way to receive a loan if your credit is not suitable. Once your credit has improved, you can add yourself back onto those loans.
Have more questions? Ready to inquire about one of our loan products? Give us a call at (866) 500 – 4500 or email us at loans@bridgewellcapital.com! We look forward to hearing from you!
Building wealth is everybody’s goal in the real estate investing business. Many investors know that profit is the name of the game, but, like in everything else, things can sometimes go wrong. Here’s a tip for successfully managing your working capital in your investing projects. If you are a perfectionist, you will find this one helpful.
One of the most common mistakes in real estate investing is failing to work out a detailed rehab budget before a project begins. Take the time to define your rehab expenses and profit margin before you start the project — you will be thankful for it. Many investors, including experienced investors, omit this step and then realize they have spent more capital than expected. This ends up affecting the bottom line and leaves room for (often unpleasant) surprises.
This is a common problem in real estate investing and is usually the result of “falling in love” with the house, not the profit. Investors falling in love with the house often make multiple upgrades to the original rehab plan, and end up putting the profit into the rehab change orders. As an entrepreneur, think about profits first, but also make sure you have made the necessary improvements to make the house marketable.
Bottom line: Carve your rehab budget into stone before you start the project and stick to that number, no matter how much you fall in love with the house.
Flip Houses for Cash-Flow, but Hold a Few Cherries as Rentals to Build Long-Term Wealth
“My favorite holding period is forever.” -Warren Buffett
There are many ways to invest in real estate. You can build your portfolio by purchasing different types of properties: apartments, single-family homes, apartment complexes, commercial buildings, office spaces, raw land, tourist locations, and even foreign properties, to name a few.
As a strategy for investment, you have 3 primary ways to make money in Real Estate Investing:
Use-change
Cash-flow
Appreciation.
When you buy a deferred maintenance house that can’t be financed conventionally and make the necessary repairs to bring the house up to FHA insurable condition, you have “used-changed” the property. Now it can be sold to an owner-occupant that can acquire long-term conventional financing. This, as you all know is the classic “Flip”. However, most wealth building in investing Real Estate incorporates the other two profit centres: cash flow and appreciation. When you flip a house, you only take advantage of only one profit centre: “use change”. When you hold property you cash in on cash-flow and long-term appreciation. Here’s how.
Profit from Inflation
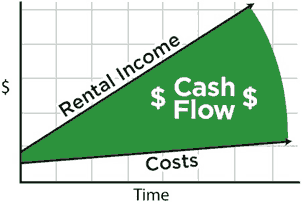
It is often said that landlords grow rich in their sleep because cash flow and equity increase over time. The average rate of inflation in the US for the past 50 years has been 4.1% annually. Therefore, if your rental income and the value of your investment property increase at this rate, your cash flow and equity will increase significantly over time. If there is a lien on the property you can still see a positive cash flow because inflation usually drives rental income up and loan payments are typically fixed.
Cash flow increases over time. Rental income goes up faster than costs because loan payments are typically fixed.
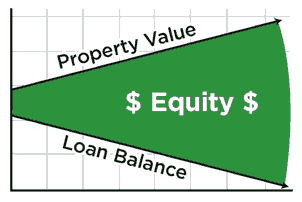
On the other hand, as equity increases over time, appreciation and loan payoff build equity.
Equity increases over time. Appreciation and loan payoff build equity.
In sum, inflation will yield profits as equity and rental income increases over time. Now think how much wealth you can build 10 years from now if you hold a few cherries as a rental; think how much wealth you can build 20 years from now… This is why Warren Buffett’s favourite holding period is forever.
The bottom line is: Flipping houses is a great source of steady cash flow for paying bills but now and then hold back a “cherry” as a rental property to add long-term wealth building to your Real Estate investing strategy.