Some real estate deals don’t need a perfect property; they need a workable plan. A building may need repairs, repositioning, or time before it qualifies for longer-term financing. Asset-based lending for real estate can provide investors with a way to finance the in-between stage when the collateral supports the transaction.
How Asset-Based Lending Works
Asset-based lenders place substantial emphasis on the value and characteristics of the real estate securing the loan. Borrower qualifications still matter, but the property itself plays a central role in determining whether the transaction is workable. Available cash can be especially important on rehab projects because borrowers may still need funds for closing costs, carrying expenses, or costs that fall outside the approved renovation budget.
Property Value and Collateral
The financed property generally serves as collateral for the loan. Lenders evaluate its value to determine how much they may be willing to lend against it. They may also consider factors such as condition, location, and property type. That means the strength of the underlying asset carries significant weight in the financing decision.
Borrower Qualifications Still Matter
Asset-based lending doesn’t mean the borrower is ignored. Lenders may still review experience, available funds, credit history, or other financial information related to the transaction. Those details can affect the loan structure and the lender’s overall view of the deal. The difference is that the property usually receives more emphasis than it would in many conventional lending situations.
When Asset-Based Lending Makes Sense
Asset-based lending can serve as a bridge between the property’s current state and the investor’s next step. This gives real estate investors time to complete improvements, stabilize income, or prepare for a future sale or refinance.
Common situations where investors may consider an asset-based loan include:
purchasing a distressed property
funding renovations to an existing property
refinancing an investment property
accessing equity through cash-out refinancing
closing a time-sensitive real estate transaction
How Property Condition Affects Financing
For renovation projects, lenders need to understand exactly where the property stands when the borrower applies. That can include how much construction is already complete, what work remains, and whether the property is far enough along to support the financing request.
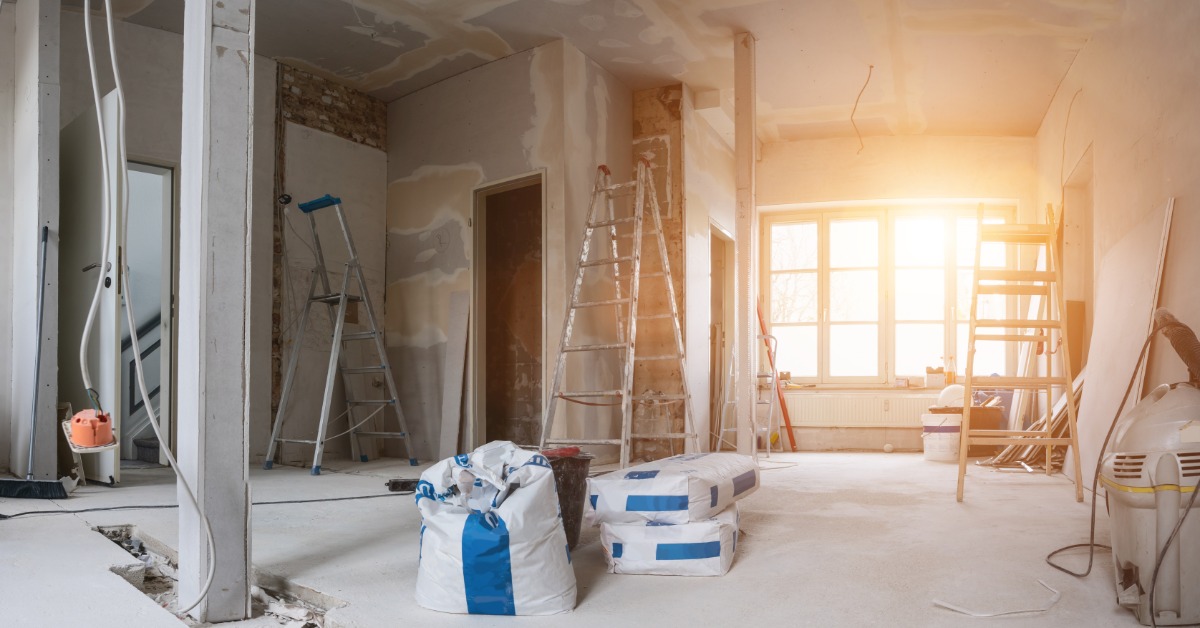
A project doesn’t always need to be finished before it can qualify for financing. At BridgeWell, our rehab-only program may finance a project once it has reached the dried-in stage, meaning an actual structure is in place. Plumbing, electrical systems, and interior finishes may still need to be completed.
How Rehab Funding Is Structured
Renovation financing may work differently from a loan in which the full amount is delivered at closing. BridgeWell’s home renovation loans use a rehab credit line, allowing borrowers to access project funds as work progresses. The program has a minimum loan amount of $100,000.
Initial Funds and Draws
Under BridgeWell’s rehab-only structure, borrowers receive 20 percent of the rehab budget upfront. Additional funds are then accessed through a draw system as the project moves forward. This can keep financing aligned with the stages of construction rather than putting the entire rehab budget in the borrower’s hands at once. Investors should understand the draw process before work begins so funding requests can be coordinated with upcoming expenses.
Interest on Used Funds
Borrowers don’t pay interest on BridgeWell rehab funds that haven’t yet been drawn. Instead, interest applies as money is accessed from the credit line. This can make the timing of each draw an important factor in managing financing costs over a longer renovation. Comparing the construction schedule with expected draws can give investors a more realistic picture of what carrying the loan may cost.
Building the Rehab Budget
A useful rehab budget should reflect the actual work required to take the property from its current condition to completion. For a partially finished project, that might mean major systems are still outstanding, while another property may primarily need interior improvements.
Common budget items may include:
plumbing and electrical work
HVAC or mechanical systems
drywall and insulation
flooring and cabinetry
fixtures and interior finishes
exterior completion work
contractor and labor costs
Preparing for Rehab Financing
The lender needs sufficient information to understand what has already been invested in the property and what financing remains required. Borrowers should be prepared to document the current construction stage, remaining scope of work, rehab budget, existing property debt, and their ownership position.
Map Out the Remaining Work
Break the project into clear stages rather than presenting the renovation as one large expense. Identifying what must happen first, what comes later, and approximately when each phase will occur makes the budget easier to evaluate. It can also make future draw requests easier to plan. This gives both the borrower and lender a clearer view of how the project should progress.
Connect Funding to the Exit
The financing plan should account for what happens after construction is finished. The property may be sold, rented, or refinanced depending on the investor’s strategy. That next step can influence how much time the borrower has to complete the work and how long the loan may need to remain in place.
Account for the Full Project Timeline
Rehab financing should account for more than the construction schedule alone. Investors may also need time for inspections, draw requests, contractor delays, leasing, marketing, or refinancing once the work is complete. Planning for those stages early can provide a more realistic picture of how long the loan may remain in place.
A complete project timeline should also account for the following:
Inspections and draw approvals may add time between construction phases.
Contractor or material delays can push back the expected completion date.
Leasing or marketing may take longer than anticipated after renovations are finished.
Refinancing can require additional documentation, valuation, and lender review.
Extra time in the schedule can give borrowers more flexibility if the project doesn’t follow the original timeline.
Asset-based lending can give rehab investors a financing structure that reflects the property’s current condition and future potential. With a clear plan for draws, remaining work, carrying costs, and repayment, borrowers can better align funding with each stage of the project. Are you planning a rehab project with a financing need of $100,000 or more? Reach out to BridgeWell to discuss available financing.
A growing business may eventually need a new location, a better layout, or improvements to its current property. Financing these changes can put substantial pressure on any budget. Owner-user loans offer businesses several benefits, including more flexibility when purchasing or improving commercial property. Here are eight distinct advantages of commercial direct lending.
Understanding Owner-User Commercial Loans
Owner-user commercial loans can finance the purchase or improvement of a property your business uses. BridgeWell’s small-balance commercial loans range from $150,000 to $2 million and can be used for a variety of eligible commercial properties.
With terms of up to five years, these loans are designed for a shorter financing window than many traditional commercial mortgages. Borrowers can use that period to complete improvements, establish operations, or prepare the property for a future refinance.
Greater Control Over Your Workspace
Leasing often comes with limits on renovations, signage, layouts, and other property changes. Buying a property or financing improvements to one you own can give your business more control over how the space supports day-to-day operations.
Customize Space for Operations
Your business may need a specific layout to serve customers, store inventory, accommodate equipment, or organize employees efficiently. Owner-user financing can support the purchase of a property with that potential or improvements that make an existing space work better. A medical office, for example, may need additional treatment rooms, while a retailer may want to rework its sales floor or storage area.
Make Long-Term Property Improvements
Businesses may feel more comfortable investing in substantial improvements when they own the property receiving those upgrades. Renovations might include new offices, updated systems, improved storage, or redesigned customer areas. Financing can make it possible to address those needs as part of a larger property plan, rather than postponing work until sufficient cash is available.
Less Reliance on Lease Renewals
Purchasing a commercial property reduces some of the uncertainty that can accompany the end of a lease. For established businesses that depend on their location, this is one of the practical benefits of owner-user loans for businesses worth considering.
Property ownership can reduce several lease-related concerns, including:
negotiating renewal terms every few years
facing rent increases at renewal
working within landlord-imposed property restrictions
relocating after a lease ends
reworking a new location for business operations
Preserve Capital for Business Needs
Buying a commercial building outright can tie up a large amount of capital that a business may prefer to keep available for operations. An owner-user loan can finance part of the purchase and, depending on the loan structure, may also support renovation or buildout work tied to the property. That can free up more capital for other priorities, such as payroll, inventory, equipment, or reserves.
Financing may also make it possible to move forward with a property that needs work rather than waiting for a finished space. Businesses comparing their options may consider forms of commercial direct lending as part of a broader acquisition or improvement plan. The right structure will depend on factors such as the property, the borrower, the scope of work, and the long-term strategy for the asset.
Flexibility With Property Condition
The right location isn’t always move-in ready when it comes on the market. Owner-user financing may provide a path for purchasing a property that needs a buildout, renovations, or other improvements before the business can use the space as intended.
Purchase Shell-Condition Space
A shell-condition property may provide the basic structure without the finished interior a business needs. For example, an office condo might still need walls, flooring, electrical work, fixtures, or other improvements before employees can move in. Financing the acquisition and planned improvements can give the owner-user more flexibility to turn an unfinished property into a functional workspace. The cost and scope of that work should still be considered alongside the purchase itself.
Complete Needed Property Improvements
Owner-user financing may also be useful when the business already has a commercial property that needs updates. The space could have outdated interiors, inefficient layouts, deferred maintenance, or areas that need repurposing. Depending on the financing structure, renovation costs may be incorporated into the broader funding plan.
Space To Support Future Growth
The space a business needs today may not be enough in the future. Buying the right property or improving the one you already own can give a company more room to plan for those changing needs.
A company may decide to purchase more square footage than it currently uses if expansion is part of its plan. It might also renovate unused or underutilized areas as staffing, inventory, equipment, or customer needs grow. Having that capacity available can reduce the need to relocate when the business outgrows its current setup.
More Flexibility in Property Use
Owner-user properties don’t always have to follow one simple occupancy arrangement. A business may purchase a building for its own operations, renovate certain areas for future use, or improve space that will serve a different commercial purpose. That flexibility can make a wider range of properties worth considering.
Possible uses for different areas of a property can include:
offices for employees or management
retail or customer-facing space
storage for inventory or equipment
areas reserved for later expansion
commercial space occupied by tenants
vacant areas awaiting renovation or future use
Opportunity To Build Property Equity
Lease payments give a business the right to use a property for a set period, but they don’t create an ownership stake. Financing a purchase can give the business an asset that may build equity over time, while strategic improvements may also strengthen the property’s usefulness and market position.
Commercial real estate can become part of the company’s broader asset base instead of remaining strictly an operating expense. Owners may also choose to invest in renovations that make the property better suited to the business. Property values aren’t guaranteed to rise, so purchases and improvements should still be evaluated based on the company’s finances and long-term plans. Even so, owning and improving the building can create an asset the business can consider in future decisions.
A business space should support the work happening inside it, not hold it back. Owner-user financing makes it easier to align the property with operational needs. It can also give the company more control over future changes. Contact BridgeWell Capital to see how we can support your commercial property needs.
Real estate investing often starts with seeing potential where others see problems. An outdated or neglected property may become a steady rental when the purchase price, repair plan, and expected income work together. Still, managing those moving parts can be difficult, especially when each decision affects the next stage of the project. The BRRRR method is a real estate investment strategy that guides investors through five stages: buying a property, renovating it, renting it, refinancing it, and repeating the process. Learn how it works and key considerations at each stage.
Buy a Property With Strong Potential
The first step is to buy a property with a clear path to improvement and steady rental demand. Before making an offer, look beyond its current condition and consider the location, layout, and types of tenants it could attract once the work is complete. A strong BRRRR property should offer enough upside to justify the repairs without pushing the total investment too high.
Calculate the Total Project Cost
Before buying, make sure you understand the expenses involved in acquiring and preparing the property. Reviewing the full project cost can help you decide whether the numbers support the investment.
A complete estimate should include:
Purchase price: The amount paid to acquire the property.
Renovation budget: The expected cost of labor, materials, and repairs.
Closing fees: The expenses required to complete the property purchase.
Financing charges: The interest, lender fees, and other costs tied to the loan.
Carrying expenses: The costs of holding the property while it’s being renovated or remains vacant.
Taxes and insurance: The property taxes and insurance premiums due during the project.
Utilities and permits: The cost of keeping services active and securing required approvals.
Unexpected repairs: Extra work that wasn’t identified before the renovation began.
Estimate the After-Repair Value
The after-repair value, or ARV, is what the property may be worth after the planned renovations are complete. Investors often estimate it by comparing the property with recently sold homes that are similar in size, location, layout, and condition. This estimate matters during the “buy” stage because it helps show whether the purchase price and repair costs leave enough room for the deal to work. A realistic ARV also gives you a better idea of how much equity may be available when it’s time to refinance.
Rehab the Property
The rehab stage focuses on making the property safe, functional, and appealing to renters. A clear plan keeps the renovation organized and prevents unnecessary spending.
Address Essential Repairs First
Start with problems that affect the property’s safety or basic function. These may include structural damage, roof leaks, or faulty electrical and plumbing systems. Completing essential repairs first creates a solid foundation for the rest of the renovation.
Choose Updates Renters Value
Once you complete major repairs, focus on improvements that fit the local rental market. Fresh paint, durable flooring, updated fixtures, and practical kitchen or bathroom changes may make the property more appealing. Investors should choose updates based on tenant needs rather than their own personal taste.
Keep the Project on Track
A realistic budget, timeline, and scope of work make the renovation easier to manage. Track expenses and progress throughout the project so you can address problems early. Leave room in the budget for repairs or delays that weren’t expected.
Rent the Property
This stage is where BRRRR begins to differ from a traditional fix-and-flip project. Rather than selling the property after renovations, the investor rents it out to create ongoing income and prepare for refinancing.
Calculate Expected Rental Cash Flow
Rental cash flow is the income left after the property’s ongoing expenses and debt payments are covered. These expenses may include taxes, insurance, maintenance, property management, utilities, vacancies, and future repairs. Even a property with strong monthly rent may produce limited cash flow if you underestimate its costs.
Prepare for Tenant Placement
Tenant placement begins with preparing the property for showings and setting a competitive rental rate. From there, investors may need to advertise the home, respond to inquiries, review applications, and complete legally compliant screening. Local rental demand will influence how quickly the property becomes occupied and whether the asking rent is realistic.
Refinance the Improved Property
Refinancing replaces the loan used to buy or renovate the property with a new one. The lender may look at the property’s completed value, rental income, and the borrower’s qualifications when setting the loan amount and terms.
If the renovations increased the property’s value, the investor may be able to cash out home equity through the new loan. This can return part of the money used for the purchase and repairs while allowing the investor to keep the property as a rental. The recovered capital may then go toward another investment or remain available as a reserve.
Repeat the Process With Another Investment
After refinancing, an investor may be able to direct some of the recovered capital toward another property. Before moving forward, it’s wise to review the first project’s actual costs, rental results, loan payments, and remaining reserves. The next purchase shouldn’t weaken the financial stability of the property that has already been completed.
Ask these questions to confirm that the first property is financially stable, and you can take on another investment:
How much capital did the refinance return?
Is the first property consistently occupied?
Does its rent cover ongoing expenses?
How much cash remains in reserve?
Which costs exceeded the original estimates?
Will another loan strain overall cash flow?
Avoid BRRRR Mistakes
The BRRRR method is widely used, but investors can run into problems if they don’t have realistic estimates. Paying too much for a property or underestimating renovation costs can leave less room for the investment to work. Investors may also run into problems when they overestimate the after-repair value, expected rent, or amount of capital the refinance will return.
An experienced lender can provide useful guidance throughout the financing process. They can explain loan requirements, review the proposed timeline, and clarify how the property’s value or rental income may affect refinancing.
The BRRRR method is a long-term strategy for improving a property, creating rental income, and reusing part of the capital invested. It works because each stage prepares the property and the investor for the next financial decision. Speak with BridgeWell Capital about funding that may fit your BRRRR project.
A promising investment property can quickly become complicated once repair estimates, closing costs, and financing deadlines come into play. Even a renovation with strong resale potential can strain an investor’s budget when important expenses are overlooked. Following practical tips for funding your next fix and flip project can help you prepare for the purchase, renovation, and eventual sale. This guide explains how to build a stronger funding plan and avoid common financial surprises along the way.
Compare Loan Structures and Requirements
Financing options can differ in how they cover the purchase, renovations, and other project expenses. Those differences can shape your costs and timeline. Compare each loan’s requirements with the property’s condition, your planned improvements, and the amount of time you expect to hold the property.
Review Rates and Loan Fees
The interest rate is only one part of the total borrowing cost. Origination fees, appraisal charges, inspection fees, and closing costs may also affect your budget. Ask the lender which expenses are due before closing and which may be included in the loan.
Understand Rehab Draw Schedules
Some lenders release renovation funds in stages rather than providing the entire rehab budget at closing. Borrowers may need to complete part of the work, request an inspection, and wait for reimbursement before receiving the next draw. Ask how inspections are scheduled and how quickly approved funds are released. The draw process should fit your contractor payment schedule and available cash reserves.
Confirm Property Eligibility
Not every lender finances the same property types or renovation scopes. Some may place limits on severely damaged homes, mixed-use properties, rural locations, or projects requiring extensive structural work. To confirm eligibility, provide the lender with accurate property details and repair estimates early in the process.
Get Preapproved Before Making Offers
Preapproval can give you a clearer idea of your potential loan amount, required contribution, and expected closing timeline. It can also help you make offers that fit your financial position instead of committing to a property before understanding the likely terms. As you consider funding your next fix and flip project, prepare the information a lender may need before you begin shopping.
Common preapproval requirements may include:
Financial background: Lenders may review your finances, credit history, bank statements, and real estate investing experience.
Property details: Provide the estimated purchase price and basic information about the home you plan to renovate.
Renovation plan: Share a preliminary repair budget, proposed improvements, and expected project timeline.
After-repair value: Estimate the property’s potential value after the planned renovations are completed.
Exit strategy: Explain whether you intend to sell, refinance, or rent the finished property.
Calculate the Full Project Budget
A realistic project budget extends beyond the purchase price and visible repairs. Account for every stage of the investment to determine how much financing and personal capital the project may require.
Estimate Purchase and Closing Costs
To fund a fix-and-flip project accurately, calculate every cost tied to buying the property before you commit. Include the purchase price, earnest money, down payment, lender fees, inspections, appraisal costs, title services, legal fees, and recording charges. Getting estimates early helps you understand how much cash you will need at closing.
Some of these expenses may not be covered by the loan. Keep enough money available to pay them without taking funds away from the renovation budget. This can help you avoid delays or cutbacks once repairs begin.
Include Holding and Selling Costs
Properties continue generating expenses while repairs are underway and while the home is listed for sale. Your budget may need to cover interest payments, insurance, utilities, property taxes, maintenance, and security. You should also plan for the cost of selling. Selling costs can include agent commissions, staging, photography, transfer fees, and buyer concessions. Estimate these expenses using a timeline that allows for possible construction or market delays.
Build a Repair Contingency
Contractor estimates cannot always account for damage hidden behind walls, floors, or ceilings. That’s why borrowers should set aside part of the rehab budget rather than allocate every dollar to planned improvements. A contingency reserve provides room for unexpected plumbing, electrical, structural, or moisture-related repairs. When surprises arise, that reserve can help keep work moving without forcing you to seek additional funding.
Verify the After-Repair Value
After-repair value, commonly called ARV, is the estimated market value of the property once renovations are complete. Review recently sold homes that are similar in location, size, layout, condition, and features. Keep in mind that properties that haven’t been renovated may not provide a reliable comparison.
Avoid basing the estimate only on the highest-priced sale in the neighborhood. Market conditions can change between the property purchase and its eventual listing date. A realistic ARV can help you decide how much to spend on the purchase and improvements without weakening the projected return.
Evaluate the Property Before Closing
A low purchase price does not always mean a property offers enough room for a profitable renovation. Inspections, title research, repair estimates, and local requirements can reveal expenses or delays that were not obvious during the initial walkthrough. Before using fix and flip loans to complete a purchase and renovation, evaluate the property as carefully as possible.
Key areas to review include:
structural and foundation damage
roof and major systems
water, mold, or pest issues
liens, permits, or code violations
zoning and allowed use
insurance and contractor availability
Prepare for the Funding Process
Loan approval does not always mean the funds are immediately ready for closing. The lender may still need an appraisal or property valuation, proof of insurance, title documentation, and other supporting information. Responding promptly and providing complete documents can prevent processing delays.
Stay in contact with the lender, closing agent, insurance provider, and contractor as the closing date approaches. Confirm which requirements remain outstanding and who is responsible for completing each one.
Plan Your Exit Strategy Early
Your intended exit should influence the loan term, renovation budget, and project timeline from the beginning. Investors who plan to sell may prioritize improvements that appeal to local buyers and support a competitive listing price. Those planning to refinance and rent the property should consider rental income, occupancy expectations, and long-term financing requirements.
Prepare a backup plan in case the preferred exit is delayed or becomes impractical. A slower market, appraisal issue, construction setback, or change in refinance terms could affect the original schedule. Knowing whether you can hold, rent, refinance, or adjust the sale price gives you more options when conditions change.
Successful fix and flip funding starts with realistic numbers, careful property research, and financing that fits the project. Review the full cost of the investment rather than focusing only on the purchase and renovation estimates. Plan for delays and unexpected expenses before they place pressure on your cash flow. With a well-prepared budget and exit strategy, you can evaluate opportunities. Speak with BridgeWell Capital about financing that keeps your next fix and flip project moving.
Real estate investing often comes down to timing, numbers, and knowing which tools fit the deal. Hard money financing can be one option when a borrower needs short-term funding for a property purchase or renovation. This complete guide explains how hard money loans for real estate work and when they may be useful. If this financing option seems like a good fit for you, a loan originator can connect you with the right lending path.
What Hard Money Loans Are
Hard money loans are short-term loans secured by real estate. Traditional lenders often look closely at credit scores, income history, debt, and long-term repayment ability to judge the project’s risk. However, the lending process for hard-money loans often places greater consideration on the property’s value, condition, and ability to support the loan.
These asset-based loans are commonly used when speed, flexibility, or property condition makes conventional financing difficult. A borrower might use one to purchase a fix-and-flip property or close on an investment opportunity quickly. In most cases, the loan is usually meant to support a specific project rather than serve as long-term financing.
How the Lending Process Works
Hard money lending can feel different from a traditional mortgage because the review is often tied closely to the real estate project itself. The process can vary by lender, but most loans involve reviewing the property, confirming the borrower’s project plan, and identifying how the loan will be repaid.
Property Evaluation
The property is usually one of the first things a lender reviews. Lenders may look at the current condition, estimated market value, repair needs, location, and potential resale or rental value. For investment projects, they may also consider the after-repair value, often called ARV. Together, these details give the lender a clearer picture of whether the property offers enough collateral for the requested loan.
Approval and Funding
Hard money loan approval can often move faster than traditional mortgage approval. The lender may still review borrower information, project details, purchase contracts, repair estimates, and comparable property values. However, the process is usually designed for real estate investors who need to act within a shorter timeline.
Exit Strategy Review
An exit strategy explains how the borrower plans to pay off the loan. Some borrowers plan to sell the property after renovations, while others plan to refinance into a long-term mortgage. A clear exit strategy helps the lender understand the full project timeline. It also helps the borrower avoid taking on a short-term loan without a realistic repayment plan.
Who Uses Hard Money Loans
Borrowers may be experienced investors expanding their portfolios or newer buyers preparing for their first short-term project. No matter their experience level, a hard money lender can determine whether the loan structure fits the project. This includes evaluating the borrower’s plan, the collateral, and the expected payoff route.
Common borrowers may include:
house flippers buying and renovating properties
real estate investors purchasing rental homes
developers working on short-term projects
landlords improving or expanding portfolios
buyers who need to close quickly
Hard money loans can support rental property purchases, bridge financing, or properties that need repairs before qualifying for conventional financing. Some borrowers use them to secure a property quickly and then refinance later.
Costs and Loan Terms
Before using any type of financing, borrowers should understand what the service includes and what it will cost. Hard money loans can have different rates, fees, repayment schedules, and timelines than traditional loans. Reviewing these details upfront helps borrowers choose financing that fits the project and budget.
Interest Rates and Fees
Hard money loans often have higher interest rates than traditional mortgage loans. This is partly because they are short-term, project-based, and may involve properties that conventional lenders view as riskier. Borrowers may also pay points, origination fees, underwriting fees, or other closing costs. Points are a form of prepaid interest or fees calculated as a percentage of the loan. Origination and underwriting fees may cover the work involved in creating the loan, reviewing the file, and confirming that the deal meets the lender’s requirements.
Repayment Schedules
A repayment schedule is the timeline for making loan payments and paying off the remaining balance. Some loans may require interest-only payments during the loan term, followed by a larger payoff when the property is sold or refinanced. Others may include different payment arrangements based on the project timeline. Borrowers should know when payments begin, when the loan matures, and what happens if the project takes longer than expected.
Loan-To-Value Ratios
Loan-to-value ratio, or LTV, compares the loan amount to the property’s value. Some lenders also consider after-repair value when evaluating renovation projects. A lower LTV may reduce lender risk, while a higher LTV may require stronger project numbers or more borrower contribution. This ratio can affect how much financing is available and how much cash the borrower may need to bring to the project.
Risks Borrowers Should Consider
Hard money loans can be helpful, but they are not the right fit for every borrower or every property. Higher rates, fees, and shorter repayment periods can create pressure if the project runs over budget or takes longer than planned.
There is also a risk in relying on an uncertain exit strategy. If a property does not sell, repairs cost more than expected, or refinancing is delayed, the borrower may incur additional costs or have difficulty repaying the loan. Careful planning reduces these risks before the loan begins.
Talking With a Lender
The first conversation with a lender usually starts with the basics of the project. They may ask about the property, the purchase price, the repairs needed, the expected closing date, and your plan for repaying the loan. From there, they can explain whether the project may qualify and what information they would need to review.
Before the call, it’s helpful to organize the details you already know. This might include the property address, estimated renovation costs, photos, comparable sales, or a possible sale or refinance plan. Having that information nearby can make the conversation more useful, even if some details are still changing.
As this guide shows, hard money loans for real estate can provide the funding needed to purchase, renovate, or move quickly on an investment property. A strong lender can help explain the process and match the loan structure to the deal. Once the loan is approved, the borrower can complete the closing requirements and access the funds according to the agreed structure. Contact BridgeWell Capital today to discuss your project and explore the right lending path.
While a rough-looking property can scare off buyers who don’t want the work, investors may see the next profitable project. Fixing the property is one big piece of the project, but finding financing that fits the timeline and end goal can be just as important. Rehab contractors can use commercial home renovation lending to prepare residential properties for resale, rental, or refinance. Here’s how this type of financing works and how it can help contractors keep repair-heavy projects moving.
Commercial Home Renovation Loan Uses
This financing option can fund repairs on residential properties used for investment purposes. It may support projects like preparing a distressed home for resale, updating a rental before tenants move in, or improving an existing property before refinancing. The loan purpose should connect to a clear business plan, not a personal home improvement project.
Investors may also use this financing when a property needs work before it fits a longer-term strategy. For example, the loan may help cover approved repair costs while the contractor manages the project timeline and exit plan.
Fund Contractor Work
Property owners can use commercial home renovation lending to pay rehab contractors for approved improvements tied to an investment property. The borrower should expect the lender to care about the work being done, who will do it, and how that work supports the property’s next step. A clear scope with costs and priorities makes the loan review smoother.
A rehab loan can help owners pay contractors because:
Approved labor and material costs may be included in the financing.
Staged payments can give contractor payouts more structure.
Repair costs stay tied to the project scope.
Owners may rely less on personal cash reserves.
The funding can support progress toward resale, rental, or refinance.
Plan the Repair Scope
A repair scope gives the owner and lender a shared starting point. It should list the work needed, the estimated cost, and the expected order of repairs. Additionally, an accurate scope helps the owner compare the loan request against the real work required.
If the contractor’s bid says one thing and the borrower’s plan says another, payment timing may get messy. Therefore, owners should clean up those details before they seek financing or sign a construction agreement.
Compare Contractor Estimates
Detailed contractor estimates help owners connect the repair plan to the loan request. A lender may want to see what work needs funding, how much each part may cost, and how those repairs support the property’s resale, rental, or refinance plan. A short, unclear quote can make the project harder to review because it leaves too many questions about labor, materials, permits, and repair priorities.
Owners should compare more than just the final price before choosing a contractor. The estimate should line up with the requested loan amount, the draw schedule, and the project timeline. Keep in mind that a cheaper bid may end up costing more later if it omits major work or causes delays.
Document Contractor Progress
Some renovation loans release funds in stages, also called draws. Instead of receiving all rehab funds upfront, the borrower may request money as work gets completed and documented. This structure helps connect financing to visible progress on the property, giving both the owner and the lender a clearer way to track how the rehab funds are being used.
Owners should keep photos, invoices, receipts, inspection notes, and signed change orders in one organized place. Those records support draw requests and give the lender a clearer view of the project. They also help the owner track what the contractor has completed and what still needs attention.
Payment timing should also match the loan structure. If the contractor expects large upfront payments but the loan releases funds after progress, the owner needs to address that gap early. A direct conversation about deposits, draws, and milestones can reduce stress during the rehab.
Prepare for Cost Changes
Even a careful estimate may miss something hidden inside an older or distressed property. Water damage, outdated wiring, structural repairs, or permit issues may appear after work begins. Because of that, owners need a backup plan before the project budget gets tight.
These planning steps can help owners prepare for cost changes:
Add a practical contingency to the budget.
Review repair priorities before work begins.
Ask contractors about likely hidden issues.
Track change orders in writing.
Keep reserves outside the loan when possible.
A loan can help fund the project, but it shouldn’t replace disciplined budgeting. The owner still needs to watch spending, approve changes carefully, and protect the project’s end goal.
Match Funding to the Exit
The owner’s end goal shapes the loan conversation by showing how the project is supposed to make financial sense. In a fix-and-flip project, the owner may need to sell the property after repairs to repay the loan and realize a profit. In a rental project, the owner may need tenants and steady income to support the next financing step. In a refinance project, the improved property value and borrower qualifications help determine whether longer-term financing is realistic.
The owner should share that exit plan before choosing a loan structure. A short-term rehab project and a longer rental hold may need different repayment expectations. Therefore, the financing should match the project’s next step, not just the repair list.
Choose the Right Fit
The right funding fit starts with the property and the plan. Owners should look at the condition of the home, the contractor’s scope, the timeline, the required cash contribution, and the final goal. Those pieces help show whether the project has a practical path.
The lender’s role is to connect the borrower’s goals with the right rehab loan structure. They may walk through payment timing, documentation needs, and possible funding limits before the owner commits to the project. With that information, the owner can plan contractor payments with fewer surprises.
Renovation projects can feel exciting at first, especially when a tired property has obvious potential. Still, the work gets easier to manage when the owner knows who borrows the money, how contractor payments may work, and what the lender needs to review. Commercial-purpose renovation financing can help property owners fund repair-heavy residential projects. Contact BridgeWell to discuss financing options for your rehab project.