Every successful flip starts with two big decisions: which property to buy and how to finance it. The funding choice shapes your timeline, renovation budget, and even your exit strategy. Investors weighing hard money versus bank loans for fix-and-flip projects quickly notice that each option comes with very different expectations. Compare these two financing solutions to determine which one best supports your plans.
Traditional Bank Loans Explained
Bank review credit, income, debt, cash reserves, tax returns, and property condition with a tighter checklist than hard money lenders. That process works well for some borrowers, but it may feel slow or rigid when a distressed property hits the market.
Banks also tend to prefer properties in good condition, which can create problems when you try to finance a true fixer-upper. If the home has major issues with plumbing, electrical systems, or habitability, the file may stall before closing. Therefore, investors who chase cosmetic-light projects may have more bank options than investors buying heavy-rehab homes.
How Hard Money Works
Hard money loans rely heavily on the property’s value and the strength of the deal. These loans work best for investors who need fast funding for time-sensitive purchases or properties that need substantial repairs.
Private lenders usually focus on the following factors:
They evaluate the property’s current value and overall condition.
They review the rehab plan to see what improvements the project includes.
They assess the borrower’s exit strategy to understand how the loan will be repaid.
Many flippers use hard money when a property needs repairs before it will qualify for conventional financing. A lender may also structure the loan around both the purchase and rehab budgets, helping investors avoid patching together several funding sources. In that sense, house flip loans give borrowers a short-term option built around buying, renovating, and selling or refinancing a residential investment property.
Speed of Funding
Time matters in a flip because good deals rarely sit around waiting for paperwork. Hard money lenders usually move faster than banks, which gives investors a better shot when sellers want a quick close. That speed can make the difference between winning the deal and losing it to another buyer.
These aspects of the lending process give hard money loans the biggest timing advantages:
Fewer approval layers and committees.
Faster review of the property and scope.
More direct communication with the lender.
Shorter path from term sheet to closing.
Better fit for auctions or urgent purchases.
Borrower Qualification Standards
Banks usually look closely at tax returns, W-2s, business income, debt ratios, liquidity, and credit history. Hard money lenders still care about borrower strength, but many place more weight on equity, property value, rehab numbers, and the exit plan. Because of that, a real estate investor with a solid deal may have more room to work with a private lender than with a traditional bank.
A borrower who does not fit a bank’s preferred profile may still qualify for a hard money loan. Factors like inconsistent taxable income, a lower credit score, limited W-2 history, or a distressed property may weaken a bank application, but they do not always carry the same weight with a hard money lender.
What Lenders Look At
A lender wants more than enthusiasm and a rough estimate from a contractor. Clear purchase terms, a sensible repair budget, local market knowledge, and a realistic sale or refinance plan make the file stronger. You can gather that information by reviewing comparable sales, getting detailed contractor bids, and studying resale trends in the neighborhood.
Property Eligibility
Property eligibility is one of the biggest differences between hard money and bank financing for fix-and-flip projects. Banks usually prefer homes that meet higher livability and appraisal standards at closing. Hard money lenders, by contrast, may work with distressed properties that require substantial repairs before they appeal to retail buyers.
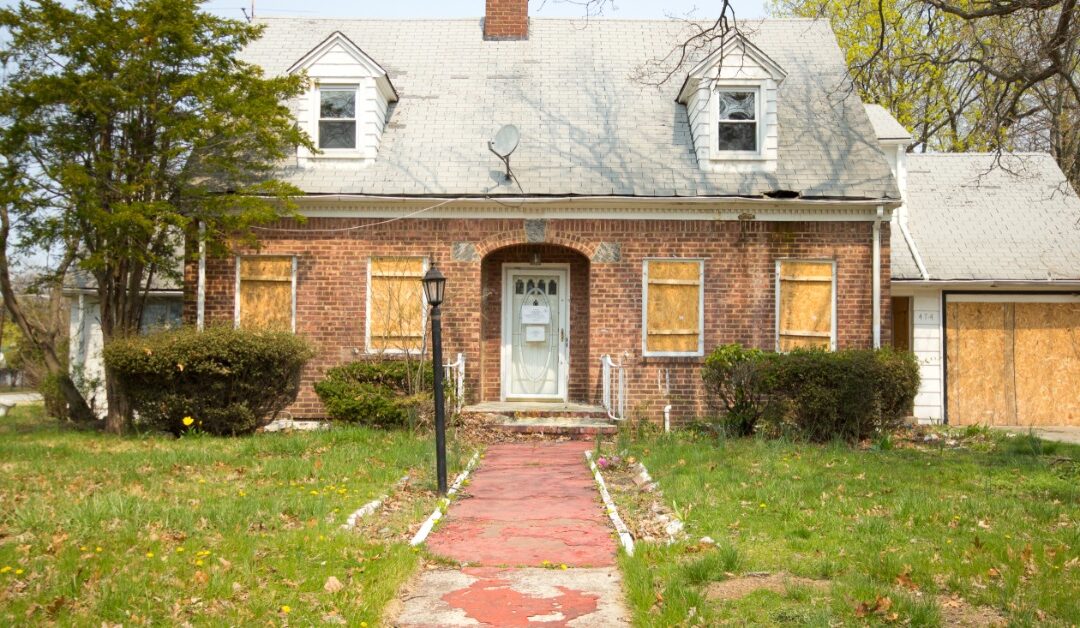
Many of the best flip opportunities need more than paint and flooring. Fire damage, outdated systems, missing kitchens, or major deferred maintenance may push a home outside a bank’s comfort zone. In some cases, property eligibility alone may make hard money loans the clear financing choice.
Down Payment Expectations
Every lender wants the borrower to have real skin in the deal. Hard money lenders commonly require a down payment, and many investors should expect something in the 20 to 35 percent range, depending on the project, experience, and leverage. That equity cushion lowers lender risk and gives the borrower a stronger starting position.
Banks may also require a meaningful down payment, though the exact amount depends on the program, property type, and borrower profile. A lower interest rate does not always mean you will bring less money to closing. Fees, cash reserves, repair costs, and delays can all raise the total amount you need upfront. Consequently, investors should compare the full cash requirement instead of focusing on one headline number.
Interest Rates and Fees
Interest rates on hard money loans usually run higher than bank loan rates. That higher cost reflects faster closings, shorter terms, asset-based underwriting, and greater flexibility on distressed properties.
An accurate comparison of loan options should include the full set of borrowing costs that affect project profit:
Interest rate over the expected hold period.
Origination points and lender fees.
Appraisal, underwriting, and closing costs.
Extension fees if the project runs long.
Carrying costs tied to delays in funding.
Loan Term and Exit
The loan term is the amount of time you have before the loan must be repaid in full. And the exit strategy is how you plan to pay it off, usually through a sale or refinance. The loan term and exit shape your budget, timeline, and overall project risk.
Hard money loans usually carry shorter terms, which fit many fix-and-flip projects built around a quick renovation and resale timeline. Bank loans may offer longer terms, but a longer timeline does not always offset slower approvals or stricter property requirements. The best choice depends on how quickly you expect to finish the project and how realistic your exit plan looks from the start.
A strong flip starts with the right financing. Choosing your loan comes down to the property, your timeline, and how you plan to exit the deal. Bank loans may be suitable for some lower-risk projects, while hard money offers investors greater flexibility on the property’s condition, closing speed, and deal structure. Reach out to a hard money lender to determine the best path to funding.
Commercial real estate loans provide capital for buying or improving properties that generate business or rental income. Between tenant shifts, surprise repair costs, and compressed closing windows, investors have little room for slow or rigid financing. In this guide to loans designed for commercial projects, we’ll break down common loan types, how they’re structured, and what lenders typically look for so you can choose funding that matches your timeline and business plan.
What These Loans Cover
Commercial loans are often used to buy, refinance, or upgrade properties that generate income or support a business. These funds can cover acquisitions, tenant-ready improvements, and renovation work that helps the property perform better. The goal is usually to support a clear next step, like stabilizing occupancy or increasing cash flow.
Because timelines can be tight, lenders often emphasize collateral strength and a realistic plan for the asset. Faster closings can help you act while pricing is favorable or the seller is ready to move. This structure makes it easier to pursue time-sensitive deals without waiting months for traditional underwriting.
Why Commercial Loans Are Unique
Commercial projects demand bigger checks, tighter timelines, and clearer math than many residential deals. A small office or retail property can still come with roof work, code updates, and vacancy carry costs that add up fast. The right financing structure gives you room to execute without draining your operating cash.
Lenders also treat commercial assets differently because income, occupancy, and utility drive value. With a flexible loan, you can act while a seller feels motivated or when a property needs quick work before it qualifies for long-term financing.
The loan terms should match how you plan to stabilize the asset and repay the balance. That way, repayment fits the timeline you’re using to boost occupancy, income, or condition.
Property Types That Qualify
Property type shapes risk, pricing, and how a lender structures the loan. General-use buildings attract more buyers and tenants, so lenders feel more comfortable with them than niche properties with limited demand. That’s why many programs focus on assets that serve multiple uses in the local market.
Here are common property types that fit small-balance commercial programs:
Office buildings.
Retail properties.
Mixed-use buildings.
Flex or light industrial spaces.
Self-storage facilities.
Small-Balance Loan Range
The loan amount and term length should support the property’s path to stronger performance. Small-balance commercial lending typically sits between residential investor loans and large institutional financing. That middle lane works well for borrowers who want a straightforward structure without the friction that comes with big-bank committees. It also fits investors who aim to grow steadily, deal by deal.
Private lenders often offer commercial loans in the $150,000 to $2 million range. Terms may run up to five years, which gives you time to stabilize, improve, and refinance or sell. Lenders may require a down payment between 20 and 35 percent, depending on the deal. Before you commit, model the deal with conservative income assumptions and realistic timelines so the term and equity needs don’t strain your cash flow.
Speed vs. Traditional Banks
Traditional banks move slowly because they stack approvals, conditions, and paperwork checks. That pace can clash with commercial deals where timing influences price, contractor availability, and lease negotiations. As a result, borrowers may lose leverage or miss the window to lock in the property.
Private lenders tend to move faster when they lend from in-house capital and focus on collateral plus feasibility. Some programs close in as quickly as 20 business days, which helps you mobilize contractors and start improvements sooner. Additionally, a faster close can strengthen your offer when a seller values certainty.
Paperwork and Qualification
Commercial borrowers usually expect income verification, tax returns, and long back-and-forth requests. Private lending can reduce that burden by focusing on deal fundamentals rather than forcing every file through the same checklist. That shift helps entrepreneurs and investors who want a simpler path to approval.
Credit and experience still matter, yet many private lenders avoid automatic disqualification based on a single metric. A weaker credit profile may still work if the asset, equity, and execution plan look strong. Additionally, newer investors can strengthen a file by engaging a capable contractor, setting a clear budget, and establishing realistic exit timing.
How Your Loan Advisor Will Help
A commercial loan advisor acts as a guide through the loan process, from initial quotes to closing. They help you position the deal by highlighting strengths like equity, a solid plan, and realistic numbers. If challenges come up, such as credit questions or tight timelines, they can suggest ways to strengthen the file and keep it viable. They also serve as your point of contact throughout the process to reduce delays and confusion.
Rehab Credit Lines Explained
Commercial projects sometimes start with distressed conditions, shell interiors, or vacant space that needs work before it produces income. In those cases, some lenders allocate part of the loan to a rehab credit line tied to improvement milestones.
Here’s what lenders typically want to see before they approve rehab funding for an existing commercial property:
A defined scope of work with phases.
A budget that reflects current pricing.
Contractor details that support execution.
A market view that supports the stabilized value.
An exit plan with clear timing.
How Renovations Get Funded
Commercial renovations can range from cosmetic improvements to a full interior repositioning. Many investors use commercial real estate loans to fund buildouts, repairs, and upgrades that strengthen leasing or prepare the asset for resale. The right financing supports the work that increases occupancy or marketability.
To keep the project on track, align the budget with the timeline. Before you close, verify how draw requests work, what inspections are needed, and when reimbursements are issued. Clear expectations help you manage cash flow and avoid delays.
With a loan designed for commercial projects, you can move from acquisition to execution without waiting on slow bank timelines. This financing solution provides capital to fund repairs, buildouts, or upgrades that support higher rent and stronger occupancy. If you’re preparing for a deal, speak with a loan advisor to get the right loan structure for your project.
A fixer-upper can be a real hidden gem. But when you’re the one uncovering its value, the budget starts climbing with every decision. New floors, fresh paint, the wiring, the roof… it all adds up, and these repairs compete for the same budget. That mix of excitement and risk is exactly why financing matters as much as the design plan. Here’s what to know about rehab loans for residential properties before you commit to a timeline, a contractor, and a closing date.
Why Rehab Loans Exist
You may be ready to buy the house and fix it up, but a traditional lender may say no because the property isn’t in livable condition yet. That creates a gap where you need funding to make repairs, but you can’t access standard financing until those repairs are done.
With a rehab loan, investors purchase a property and fund improvements without waiting for the home to be move-in ready. That speed matters when you’re competing for distressed inventory and tight closing windows.
At the end of the project, your exit plan is how you’ll pay off the loan and move on to the next deal. Many investors either sell the renovated home for a profit or refinance into longer-term financing once the property is finished and stabilized. Your exit plan affects how much rehab work makes sense, how long you can hold the property, and what loan terms fit your timeline.
Property Condition Requirements
Every lender sets its own starting condition rules, which shape which properties qualify for the rehab loan. At BridgeWell Capital, we finance “dried-in” properties, meaning they have a roof plus windows and doors in place to protect the interior from weather. That baseline gives the project a workable starting point while you handle the rest of the improvements.
How Lenders Evaluate Deals
Hard money lenders typically evaluate the property’s future potential rather than judging the loan solely on today’s condition. They’re underwriting the path from “needs work” to “finished product,” which means they care about how your plan translates into value. Because of that, your pricing, scope, and resale or refinance plan are important in the approval conversation.
Purchase Price
The purchase price is what you pay to acquire the property, and it sets the foundation for the entire deal. If you overpay, you squeeze your budget and your exit options before renovations even begin. A realistic purchase price also helps the lender feel confident that the deal has room for profit once you account for costs and the time needed to finish the work.
Renovation Budget
The renovation budget is the line-by-line plan for what it will cost to bring the property from its current condition to your finished target. It should go beyond cosmetic upgrades and account for demo work, labor, materials, permits, utility setup, cleanup, and disposal, plus a cushion for surprise issues. You should build the renovation budget from actual quotes and local costs, so it serves as a practical plan rather than a shaky estimate.
Lenders compare your budget to the scope of work and the standards set by renovated nearby sales, because the end product must match what buyers pay for in that area. If the budget comes in too low, they may worry you’ll stall mid-rehab or cut corners that hurt value and marketability. If it comes in too high, they may flag over-improving, where you spend beyond what the neighborhood supports and shrink your potential return.
After-Repair Value (ARV)
ARV is the estimated value of the property after the renovation work is completed. Lenders rely on comparable sales and market context to evaluate whether your ARV target is realistic. If the ARV is overstated, the deal’s margins shrink on paper, and the lender may reduce loan proceeds or pass on the project altogether.
Separating Rehab Wants From Needs
Not every rehab task matters equally, so you’ll want to sort tasks by urgency before you set your budget and timeline. Some repairs protect the property and keep the project moving, while other upgrades improve how the home looks and sells. Once you know what’s essential versus optional, you can spend money in the places that support your exit plan.
Safety And Water Protection
First, focus on issues that keep the house safe and dry, because water damage and hazards can snowball into bigger repairs. Items like roof leaks, active plumbing issues, and electrical risks can stop work, trigger code problems, or damage new materials.
Systems And Mechanical Updates
Next, address mechanical systems, including HVAC, plumbing, and electrical. Buyers and appraisers care about these items because they affect comfort, reliability, and long-term maintenance costs. Updating these systems when needed enhances resale appeal.
Layout And Function Fixes
After addressing hazards and mechanical systems, consider changes that improve how the home feels, such as by opening tight spaces or correcting awkward flow. These updates can boost perceived value because buyers react quickly to usable layouts and practical storage. Even small function upgrades, like adding laundry space or improving lighting, can make a home feel more “finished.”
Cosmetic And Market-Facing Finishes
Finishes like kitchens, baths, flooring, and paint help the property compete with renovated homes in the same area. These upgrades influence first impressions, photos, and showings, which matter when you want a faster sale. Match the finish level to neighborhood expectations to avoid overbuilding.
Draws, Timelines, And Cash Flow
Rehab loans typically release renovation funds in stages as work progresses. This draw structure keeps spending tied to visible progress and helps track the scope. It also means you need a cash-flow plan for labor and materials between draw requests.
Importantly, draw timing affects decisions such as ordering materials and scheduling crews. You’ll want photos, receipts, and quick updates ready so requests move smoothly. A steady communication rhythm with your contractor keeps paperwork from turning into a scramble.
Rehab Loans Provide Streamlined Approvals
A rehab loan is financing that supports both the purchase and the renovation of a fixer-upper. With solid numbers and a clear priority list, you’ll have a clearer path to either sell the finished home or refinance it after the rehab. If you need to close fast, it helps to know rehab loans for residential properties can move quickly thanks to streamlined approvals.
With a rehab loan from BridgeWell Capital, you get 20 percent of your budget up front to kick off the work after closing. That upfront cash can cover early-phase needs like demo, dumpsters, deposits, and material orders that contractors expect before they start. It helps you keep crews moving instead of pausing while you wait for the first draw. Reach out to us today to start your application.
Residential real estate moves quickly, and hesitation can cost you a deal. Buyers who act decisively tend to secure stronger opportunities in competitive neighborhoods. Fix-and-flip loans provide fast funding for residential investors who need capital lined up before submitting offers. With the right financing in place, projects move from purchase to resale without unnecessary delays.
What Are Fix-and-Flip Loans?
Fix-and-flip loans provide short-term capital to purchase and renovate residential properties. Investors use them to acquire homes that need repairs, upgrades, or repositioning before resale. Unlike traditional mortgages, these loans focus more on property value and project potential than long-term income documentation.
Lenders evaluate the asset, scope of work, and projected after-repair value. This approach supports quicker approvals and flexible timelines. As a result, investors can act when opportunities appear instead of watching them disappear.
Asset-Based Lending Explained
Asset-based lending centers on the property’s after-repair value (ARV) rather than solely on borrower income. That evaluation helps determine loan amounts and terms.
This structure aligns with properties that may not qualify for conventional financing because of their condition. Distressed homes, for example, rarely meet standard underwriting guidelines. Asset-based financing creates a workable path forward.
Lenders typically consider the following criteria when making asset-based underwriting decisions:
The property purchase price in relation to current market comparables.
A realistic renovation budget supported by contractor bids.
The projected after-repair value based on recent comparable sales.
The borrower’s experience with similar renovation projects.
A defined exit strategy outlining resale or refinance timing.
Why Speed Matters in Flipping
Inventory turns over quickly in desirable neighborhoods, and well-priced homes rarely sit on the market for long. Sellers favor buyers who can close quickly and show clear proof of funds. Fix-and-flip loans provide fast funding for residential investors working against tight acquisition and renovation timelines.
Underwriting delays in traditional loans can disrupt contractor schedules and push back material orders. As funding slows, renovation timelines become compressed and harder to manage. In contrast, quick fix-and-flip loans maintain momentum and allow investors to lock in labor and material pricing early.
How The Loan Process Works
Financing a fix-and-flip project follows a step-by-step structure that moves from evaluation to repayment. Knowing what happens at each stage helps investors prepare documentation, anticipate timelines, and keep projects on schedule.
Initial Deal Submission
The process begins when the investor submits details about the property and renovation plan. This typically includes the purchase contract, scope of work, budget estimates, and comparable sales. Lenders review the acquisition price alongside the projected after-repair value to assess overall feasibility. Early evaluation helps determine possible loan size and required equity contribution.
Underwriting And Valuation
During underwriting, the lender analyzes the financial strength of the deal. This review focuses on renovation costs, resale projections, market comps, and the borrower’s experience. An appraisal or valuation may be ordered to support the after-repair value estimate. Thorough documentation helps move this stage forward efficiently.
Loan Structuring And Terms
Once underwriting supports the deal, the lender outlines proposed loan terms. These terms typically include interest rate, origination points, loan-to-value limits, and the draw schedule. The investor reviews the term sheet to confirm alignment with projected returns. Once the borrower and lender agree to the structure, the loan moves forward to closing.
Closing And Acquisition Funding
At closing, both parties finalize and sign the loan documents. The investor contributes the required down payment and pays agreed fees. Loan funds are then disbursed to complete the property purchase. Ownership transfers at this stage, and the renovation timeline begins.
Renovation Draw Schedule
Renovation funds are released in stages rather than all at once. The lender establishes a draw schedule tied to project milestones or completed work. Investors submit draw requests as phases of construction finish, sometimes accompanied by inspections or progress reports.
Exit And Loan Repayment
The final stage centers on repaying the loan according to the agreed exit strategy. Most investors sell the renovated property and use the proceeds to repay principal, interest, and fees. Some choose to refinance into a longer-term loan if they plan to hold the property. Successful execution of the exit concludes the fix-and-flip cycle and frees capital for the next opportunity.
Approval Timeline Overview
Every fix-and-flip deal moves at a different pace, but investors can shorten the timeline by providing clear documentation. When lenders receive organized budgets, contractor bids, and resale comps upfront, they can evaluate the project without delays.
Private lenders typically close faster than traditional banks because they focus on asset value and project feasibility. This streamlined process reduces layered approvals and committee reviews. Faster closings give investors stronger negotiating power in competitive markets.
Costs and Loan Terms
Fix-and-flip loans typically carry shorter terms than standard mortgages. Investors repay the loan after selling the property or refinancing into longer-term financing. Interest rates reflect the short duration and speed of funding.
Equity requirements vary based on the property, the borrower’s experience, and the overall risk profile. Lenders typically require investors to contribute cash upfront to demonstrate commitment to the project. This shared investment structure promotes accountability and supports stronger lender confidence.
Interest And Points Breakdown
Short-term fix-and-flip loans typically include interest charges along with origination points as part of the total cost of borrowing. Interest accrues over the life of the loan, while points are charged upfront at closing. Together, these costs make up the primary expense of short-term financing.
One origination point typically equals one percent of the total loan amount. For example, two points on a $300,000 loan equal $6,000 in upfront fees. Investors pay these points at closing, so they must factor them into their capital requirements.
Compared To Traditional Mortgages
Traditional mortgages focus on long-term occupancy and borrower income. Fix-and-flip loans center on short-term project execution. This difference shapes underwriting and timelines.
Banks require extensive documentation and property condition standards. Properties that require major repairs, lack functional systems, or exhibit deferred maintenance are typically unable to meet conventional appraisal and habitability guidelines. Private financing offers flexibility aligned with renovation work.
Choosing The Right Partner
Private lending varies widely in process, service level, and turnaround times. The private lender’s operational models influence speed and consistency.
These lender practices make funding more efficient:
In-house underwriting rather than outsourced review.
Defined timelines for approvals and closings.
Experience with residential rehab projects.
Straightforward documentation requirements.
Accessible support during renovation draws.
Successful flips rely on more than a good purchase price; they require financing that keeps pace with construction and resale goals. Fix-and-flip loans provide short-term capital structured around after-repair value and defined exit strategies. Investors who understand loan terms, costs, and approval timelines position themselves for smoother execution. If you’re planning your next renovation, connect with BridgeWell Capital to explore funding options that keep your project moving without delays.
Real estate investors constantly look for ways to unlock capital without selling strong-performing properties. A cash-out refinance is a loan that replaces your existing mortgage with a new, larger mortgage, allowing you to take the difference in cash. For investment properties, this financing option provides several benefits, including the opportunity to redeploy built-up equity into additional income-producing assets. See how you can use this strategy to gain greater financial flexibility and grow your portfolio.
Access Built-Up Equity
Investment properties gain value as markets appreciate and loan balances decline. That difference between market value and remaining debt represents usable equity. A cash-out refinance allows you to replace your existing mortgage with a new loan for a higher amount and receive the difference in cash. With a cash-out refi, you tap into capital while maintaining ownership and control of the asset.
Equity access creates flexibility during growth phases. Rather than waiting to sell, you convert dormant value into working capital. As a result, you keep long-term appreciation potential while strengthening your short-term liquidity.
Understanding Loan-To-Value Ratios
Lenders evaluate how much equity you can access through the loan-to-value ratio, or LTV. Most investment property refinances allow borrowing up to a set percentage of the property’s appraised value. A lower LTV typically results in stronger terms and lower perceived risk. Maintaining a solid equity cushion strengthens your approval profile and can lead to more favorable loan pricing.
Improve Cash Flow Stability
Refinancing creates an opportunity to adjust loan terms and monthly payments. A lower interest rate or extended amortization schedule can reduce your monthly obligations. That shift improves cash flow, especially when rents remain stable or increase. Over time, improved margins strengthen portfolio resilience.
Investors also use refinancing to consolidate higher-interest debt tied to the property. Replacing expensive financing with structured, long-term capital smooths operating expenses. Additionally, predictable payments make budgeting easier, which supports more confident decision-making across multiple properties.
Rate and Term Optimization
Loan structure influences profitability as much as rental income. Shorter terms build equity faster but increase monthly payments. Longer terms reduce payments while stretching repayment over time. Choosing the right structure depends on your broader strategy and risk tolerance.
Fund Additional Acquisitions
Growth requires capital, and equity provides a powerful source. By extracting funds from one property, you create buying power for the next opportunity. That approach keeps your portfolio expanding without liquidating strong assets. Many seasoned investors rely on recycled equity to scale.
The proceeds from a refinance can serve as down payments, renovation budgets, or bridge capital. A well-timed refinance strengthens your ability to submit compelling offers.
The most common ways investors deploy refinance proceeds include:
Down payments on new rental properties.
Value-add renovations that increase rent.
Paying off short-term bridge loans.
Covering closing costs on acquisitions.
Funding reserves for future opportunities.
Renovate Without Selling
Even properties in need of improvement can continue to generate rental income. Through refinancing, investors can access capital to fund renovations without giving up ownership of the asset. Well-planned upgrades can support higher rents and long-term appreciation, all while preserving ownership.
Improvements also attract stronger tenants and reduce turnover. Additionally, fresh updates justify higher lease rates in competitive neighborhoods. And enhanced curb appeal can support a higher resale value if you exit later.
Strategic Value-Add Improvements
Targeted upgrades typically deliver the best return. Start with high-visibility areas like kitchens and bathrooms, where modest updates can make a strong impression. Functional improvements, such as new appliances or updated cabinetry hardware, often deliver measurable rental upside.
Evaluate the local rental market before committing to large-scale renovations. You should make improvements that reflect what comparable properties offer so that spending supports achievable rent increases.
Consolidate High-Interest Debt
During acquisition, many investors use financing that carries higher interest rates. Refinancing into longer-term financing reduces the overall cost of capital. This adjustment improves profitability over the life of the property.
Debt consolidation simplifies financial management as well. Instead of juggling multiple payments, you manage one structured loan. Additionally, reduced interest expense increases net operating income, thereby improving cash flow stability and enhancing overall property performance.
Strengthen Financial Flexibility
Financial flexibility is a significant benefit of cash-out refinancing for investment properties. Converting built-up equity into accessible capital creates a cushion that supports defensive planning, strategic growth, and portfolio stability.
Covering Vacancies And Repairs
Unexpected vacancies and property repairs can interrupt steady cash flow. Accessible reserves allow investors to cover mortgage payments, maintenance costs, and operating expenses without strain. That financial buffer protects property performance during temporary disruptions.
Reducing Risk During Expansion
Growth introduces new exposure, especially when acquiring additional properties. Liquidity reduces rushed financing decisions. Investors expand more confidently when they maintain capital reserves alongside new acquisitions.
Navigating Market Downturns
Rental demand and property values fluctuate over time. Investors with accessible capital manage downturns without forced sales or distressed refinancing. Strong liquidity supports stability while markets recover.
Acting Strategically On New Deals
Opportunities rarely wait for capital to catch up. Investors with available funds can move quickly when undervalued properties hit the market. Financial flexibility enables deliberate decision-making rather than reactive scrambling for financing.
Replace Risky Short-Term Loans
Short-term financing helps secure properties quickly. However, those loans frequently include a short interest-only period followed by balloon payments or much higher rates. Refinancing into stable, longer-term debt reduces rollover risk. Investors gain predictability and breathing room.
Stable financing supports long-term rental strategies. Instead of worrying about looming maturities, you focus on operations and tenant retention. Additionally, predictable payments improve cash flow forecasting and support more accurate long-term planning.
The key risks that refinancing can help address include:
Balloon payments approaching maturity.
Rising variable interest rates.
High monthly debt service.
Limited renewal options with current lenders.
Tight covenants restricting flexibility.
Scale Portfolio Strategically
Growth without structure can strain both capital and operations. A well-planned refinance strategy allows investors to expand deliberately rather than react impulsively. By redeploying equity in a measured way, portfolios remain balanced and positioned for sustainable scaling.
Defined targets should shape when and how much to refinance. Some investors prioritize stabilized income before refinancing, while others focus on appreciation milestones. Accurate valuations and realistic projections provide the data to make confident, disciplined choices.
Choosing the Right Lending Partner
Lender selection affects speed, terms, and overall experience. Investment property refinancing involves different underwriting criteria than primary residences. Working with a lender familiar with investor needs streamlines the process.
Investors should review rates, loan-to-value limits, and repayment structure before moving forward. A well-structured cash-out refinance supports both immediate liquidity and long-term strategy.
Investment properties build equity over time, and refinancing allows you to put that value to work. From improving cash flow to funding acquisitions and reducing risk, a cash-out refi supports disciplined portfolio management. Strategic timing and structured terms make the difference between reactive borrowing and intentional growth. Connect with a knowledgeable lending partner to evaluate how a cash-out refi can advance your long-term investment objectives.