Some real estate deals don’t need a perfect property; they need a workable plan. A building may need repairs, repositioning, or time before it qualifies for longer-term financing. Asset-based lending for real estate can provide investors with a way to finance the in-between stage when the collateral supports the transaction.
How Asset-Based Lending Works
Asset-based lenders place substantial emphasis on the value and characteristics of the real estate securing the loan. Borrower qualifications still matter, but the property itself plays a central role in determining whether the transaction is workable. Available cash can be especially important on rehab projects because borrowers may still need funds for closing costs, carrying expenses, or costs that fall outside the approved renovation budget.
Property Value and Collateral
The financed property generally serves as collateral for the loan. Lenders evaluate its value to determine how much they may be willing to lend against it. They may also consider factors such as condition, location, and property type. That means the strength of the underlying asset carries significant weight in the financing decision.
Borrower Qualifications Still Matter
Asset-based lending doesn’t mean the borrower is ignored. Lenders may still review experience, available funds, credit history, or other financial information related to the transaction. Those details can affect the loan structure and the lender’s overall view of the deal. The difference is that the property usually receives more emphasis than it would in many conventional lending situations.
When Asset-Based Lending Makes Sense
Asset-based lending can serve as a bridge between the property’s current state and the investor’s next step. This gives real estate investors time to complete improvements, stabilize income, or prepare for a future sale or refinance.
Common situations where investors may consider an asset-based loan include:
- purchasing a distressed property
- funding renovations to an existing property
- refinancing an investment property
- accessing equity through cash-out refinancing
- closing a time-sensitive real estate transaction
How Property Condition Affects Financing
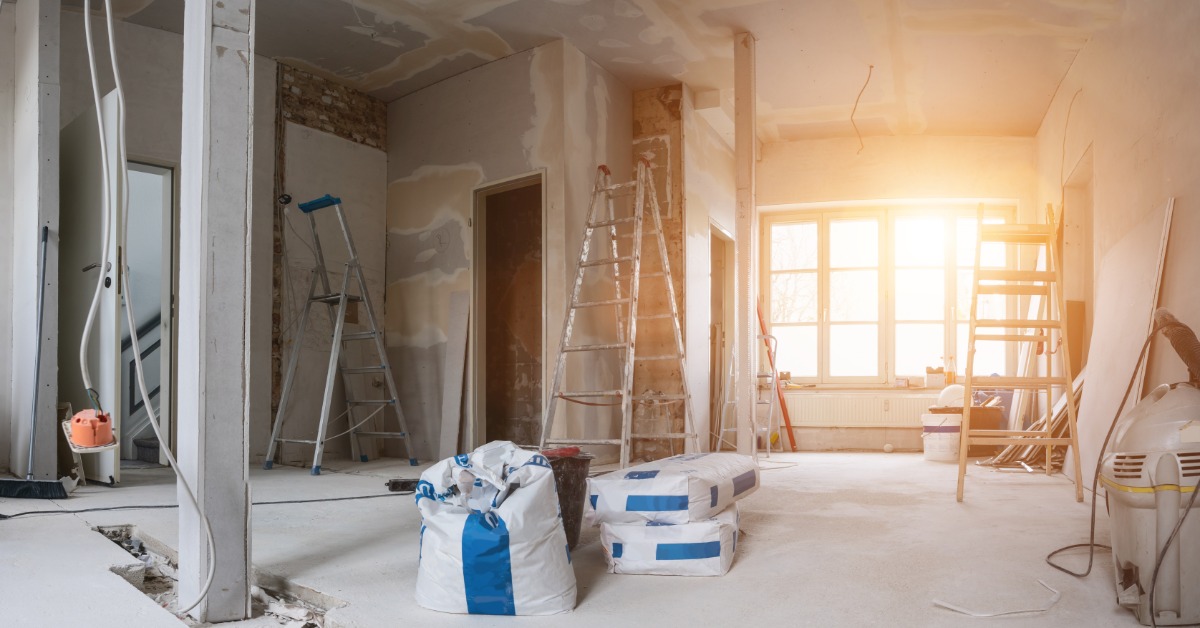
For renovation projects, lenders need to understand exactly where the property stands when the borrower applies. That can include how much construction is already complete, what work remains, and whether the property is far enough along to support the financing request.
A project doesn’t always need to be finished before it can qualify for financing. At BridgeWell, our rehab-only program may finance a project once it has reached the dried-in stage, meaning an actual structure is in place. Plumbing, electrical systems, and interior finishes may still need to be completed.
How Rehab Funding Is Structured
Renovation financing may work differently from a loan in which the full amount is delivered at closing. BridgeWell’s home renovation loans use a rehab credit line, allowing borrowers to access project funds as work progresses. The program has a minimum loan amount of $100,000.
Initial Funds and Draws
Under BridgeWell’s rehab-only structure, borrowers receive 20 percent of the rehab budget upfront. Additional funds are then accessed through a draw system as the project moves forward. This can keep financing aligned with the stages of construction rather than putting the entire rehab budget in the borrower’s hands at once. Investors should understand the draw process before work begins so funding requests can be coordinated with upcoming expenses.
Interest on Used Funds
Borrowers don’t pay interest on BridgeWell rehab funds that haven’t yet been drawn. Instead, interest applies as money is accessed from the credit line. This can make the timing of each draw an important factor in managing financing costs over a longer renovation. Comparing the construction schedule with expected draws can give investors a more realistic picture of what carrying the loan may cost.
Building the Rehab Budget
A useful rehab budget should reflect the actual work required to take the property from its current condition to completion. For a partially finished project, that might mean major systems are still outstanding, while another property may primarily need interior improvements.
Common budget items may include:
- plumbing and electrical work
- HVAC or mechanical systems
- drywall and insulation
- flooring and cabinetry
- fixtures and interior finishes
- exterior completion work
- contractor and labor costs
Preparing for Rehab Financing
The lender needs sufficient information to understand what has already been invested in the property and what financing remains required. Borrowers should be prepared to document the current construction stage, remaining scope of work, rehab budget, existing property debt, and their ownership position.
Map Out the Remaining Work
Break the project into clear stages rather than presenting the renovation as one large expense. Identifying what must happen first, what comes later, and approximately when each phase will occur makes the budget easier to evaluate. It can also make future draw requests easier to plan. This gives both the borrower and lender a clearer view of how the project should progress.
Connect Funding to the Exit
The financing plan should account for what happens after construction is finished. The property may be sold, rented, or refinanced depending on the investor’s strategy. That next step can influence how much time the borrower has to complete the work and how long the loan may need to remain in place.
Account for the Full Project Timeline
Rehab financing should account for more than the construction schedule alone. Investors may also need time for inspections, draw requests, contractor delays, leasing, marketing, or refinancing once the work is complete. Planning for those stages early can provide a more realistic picture of how long the loan may remain in place.
A complete project timeline should also account for the following:
- Inspections and draw approvals may add time between construction phases.
- Contractor or material delays can push back the expected completion date.
- Leasing or marketing may take longer than anticipated after renovations are finished.
- Refinancing can require additional documentation, valuation, and lender review.
- Extra time in the schedule can give borrowers more flexibility if the project doesn’t follow the original timeline.
Asset-based lending can give rehab investors a financing structure that reflects the property’s current condition and future potential. With a clear plan for draws, remaining work, carrying costs, and repayment, borrowers can better align funding with each stage of the project. Are you planning a rehab project with a financing need of $100,000 or more? Reach out to BridgeWell to discuss available financing.